Authored by Anthony Milewski of The Oregon Group,
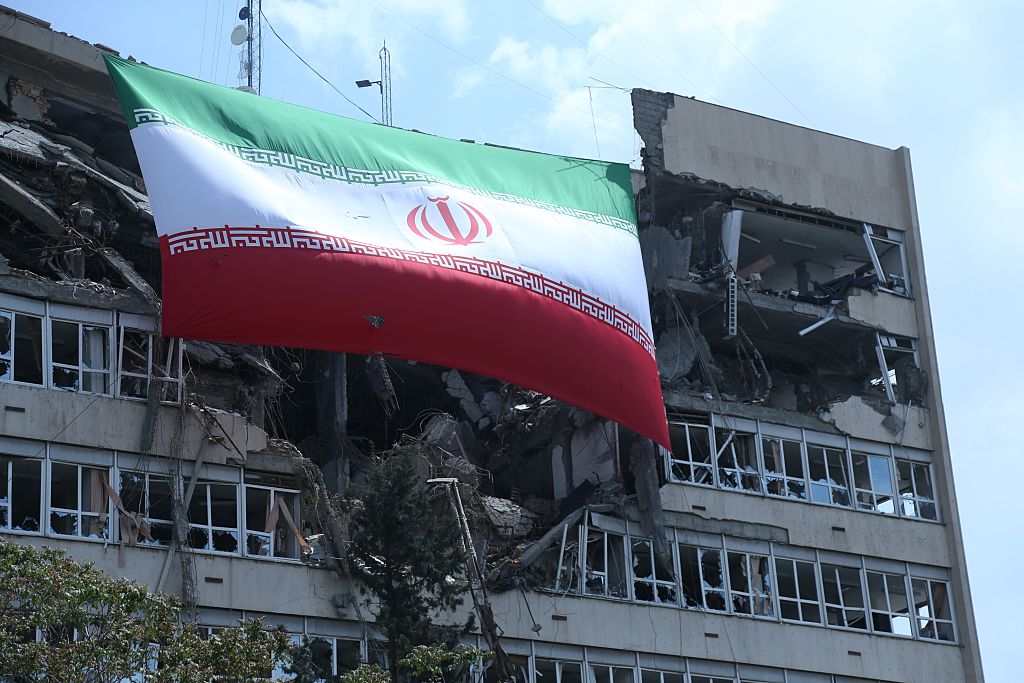
Sixteen days of the Iran war left coalition forces needing an estimated 4,000kg of tungsten just to replace the expended gun ammunition — but US mines produced none of the metal in 2025 and, instead, China accounted for 79% of global tungsten mine production.
And it's not just tungsten.
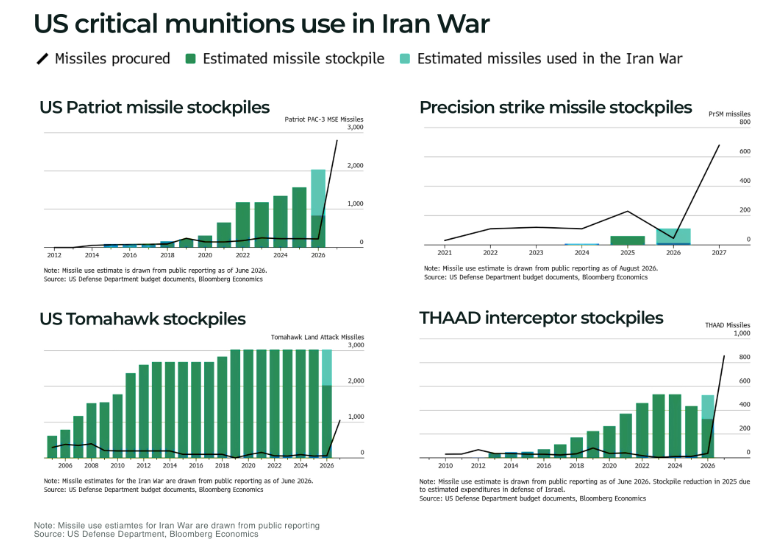
In a RUSI analysis of the Iran war, researchers estimated coalition forces expended more than 11,000 munitions in the first 16 days. And replenishing these arsenals will require secure access to a wide range critical minerals — from antimony to copper, rare earths to titanium — that make advanced weapon systems possible.
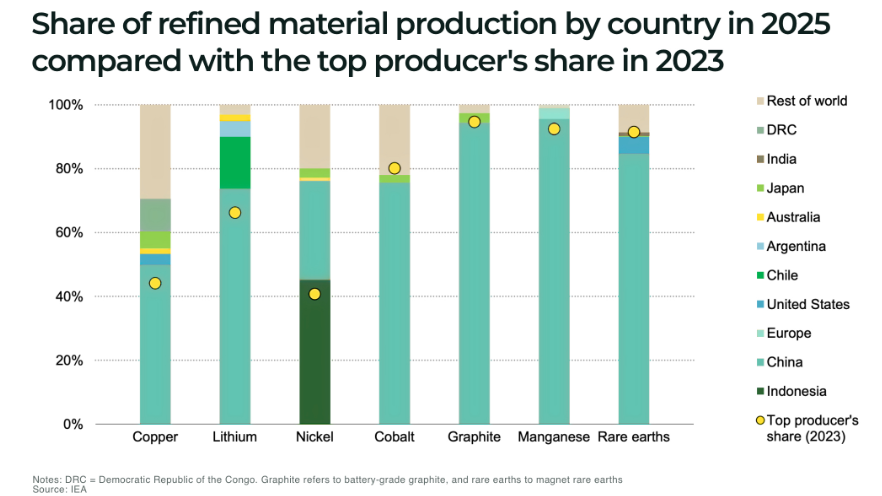
And the West's exposure, especially dependence on Chinese supply, is substantial.
"If the war in Ukraine was a wake-up call for the Western defence industrial base, the first 16 days of the Iran conflict are a fire alarm signalling a crisis of endurance" — Over 11,000 munitions in 16 Days of the Iran War: 'Command of the Reload' Governs Endurance
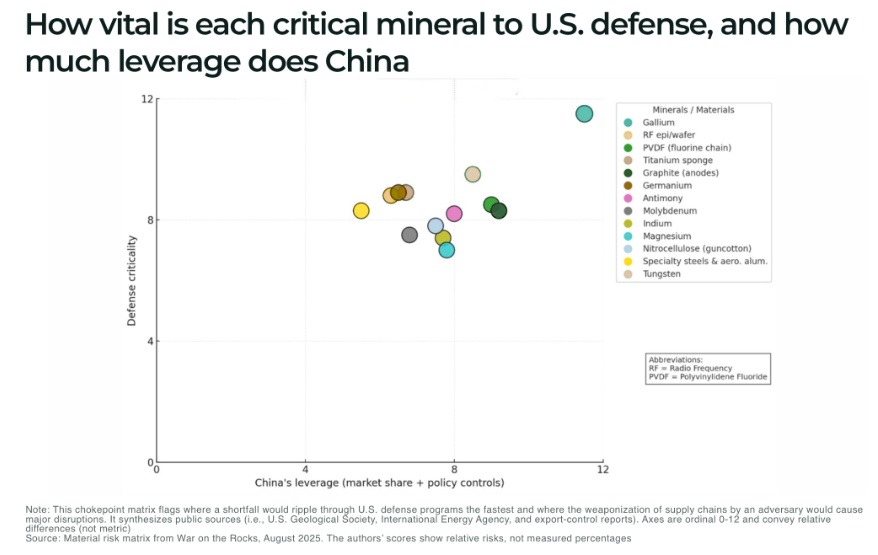
Material risk matrix from War on the Rocks, August 2025. The authors' scores show relative risks, not measured percentages.
The critical mineral risks behind the weaponry
In their August 2025 War on the Rocks analysis, Macdonald Amoah, Morgan Bazilian, Clarkson Kamurai and Jahara Matisek, ranks across two broad tiers:
- first-tier risks are gallium, the battery-chemicals chain, tungsten, and graphite
- second tier includes titanium sponge, germanium, antimony, indium, magnesium, and molybdenum, with nitrocellulose and finish-line capacity in specialty steels and aerospace aluminum (requiring near-term hedges because surge capacity is slow to add)
The assessment combines concentration of supply, military importance, limited substitutes and the time needed to add capacity. For example, refining, separation and specialised finishing are frequent constraints if a mine whose output still passes through a vulnerable refining process that leaves part of the exposure intact.
Across ammunition, missiles and supporting military systems, six critical mineral priorities stand out:
- Magnet rare earths, including samarium, specialised magnets support military aircraft, missiles and control systems, making a secure supply chain from mining through magnet production strategically important
- Tungsten, its role in armaments, turbine alloys and metalworking tools connects mineral supply to both weapons and the equipment used to manufacture them
- Antimony, antimony trisulfide is used in ammunition primers; defence support for Perpetua's military-specification antimony programme connects mine development to that requirement
- Gallium, its semiconductor applications support radar and military communications; the Pentagon announced a US$174 million investment in planned Australian gallium production in August 2026
- Germanium, infrared optics and thermal-sensing equipment need dependable material supply; the Defense Logistics Agency has supported domestic recycling of optical-grade germanium
- Titanium, strong, lightweight materials are essential to military aerospace; defence backing for IperionX's domestic titanium supply chain illustrates the effort to expand alternative supply
For example, tungsten and gallium illustrate America's (and the West's) vulnerability because they underpin both weapons and the systems that support them: tungsten is used in armaments and the cutting tools needed to manufacture military equipment, while gallium enables semiconductors used in advanced military radars. Yet, China accounted for approx 79% of global tungsten mine production and 99% of primary low-purity gallium production in 2025, exposing these capabilities to highly concentrated mineral supply chains.
An arsenal built on imported minerals
US vulnerability extends across the critical-mineral supply chain.
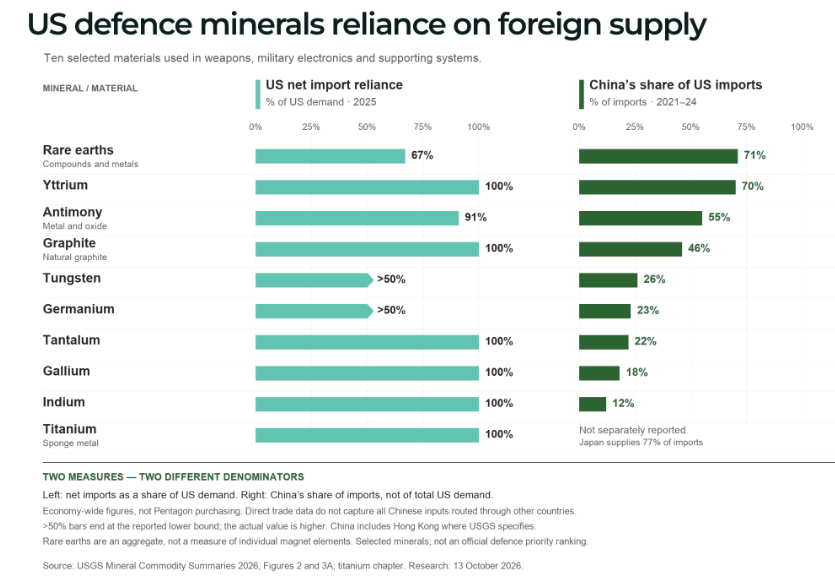
A July 2026 Government Accountability Office assessment reported that the US was fully import-dependent for 12 critical minerals and relied on imports for at least half its requirements for another 34.
USGS Mineral Commodity Summaries 2026. Total import reliance is for 2025; China's share of imports covers 2021–24. The two measures have different denominators
Despite recent government funding, the scale of the challenge for the US remains significant, for example:
- recycling and substitution can help, but their contribution varies, with the US Government Accountability Office warning that alternatives for semiconductor minerals such as gallium are unlikely to reduce import dependence significantly in the near term.
- the antimony supply crisis illustrates the scale of that challenge with S&P Global's August 2026 assessment estimating that, even if announced projects proceed, smelting capacity outside China could remain approximately 27% below projected demand outside China in 2030. It also warned that new processing facilities could face shortages of mine feedstock
- a 2026 Hoover Institution policy paper, citing Stanford research, recounts a defence contractor tracing a titanium supply chain through 13 tiers to Chinese mines and transport infrastructure — leading directly to "Chinese mines, Chinese roads, and Chinese trucks"
The Pentagon is increasingly explicit about the stakes.
"Securing resilient domestic and allied supply chains is a fundamental warfighting requirement," said Mike Cadenazzi, the Pentagon's assistant secretary responsible for industrial base policy, in an August 2026 announcement committing US$750 million to secure rare-earth supply from Brazil's Serra Verde.
Acting Secretary of the Army Honorable Adam Telle recently announced the Army's first‑ever "Manufacturing Rodeo", describing it as a competitive stress test for both the Army's organic industrial base and the nation's broader manufacturing network.
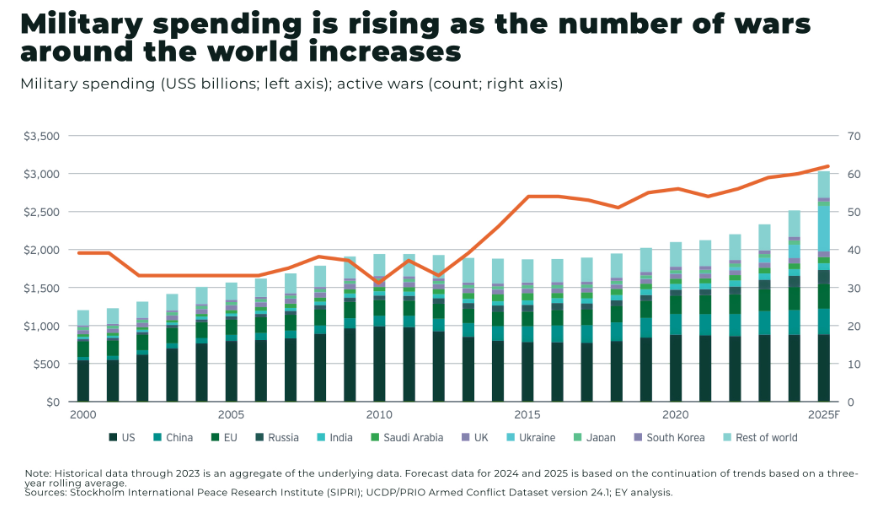
Meanwhile, the mineral demands of military rearmament are becoming more pressing. Global military expenditure reached a record US$2.887 trillion in 2025, with European spending rising 14% in real terms. US expenditure fell that year, but the wider rearmament cycle continued. Larger budgets create purchasing power; they cannot immediately create additional mineral supply.
Tungsten shows why securing supply takes more than money
The four tonnes of tungsten used in the weapons fired in the 11 days of the Iran War is a relatively small quantity in the wider tungsten market (the US imported an estimated 11,700 tonnes of tungsten in 2025) — but securing dependable supplies outside China increasingly means committing years ahead.
In July 2026, US processor Global Tungsten & Powders extended its agreement for approximately 90% of Sangdong's first-phase production to 21 years; buyers seeking additional material face a market where substantial volumes of new supply already have a customer.
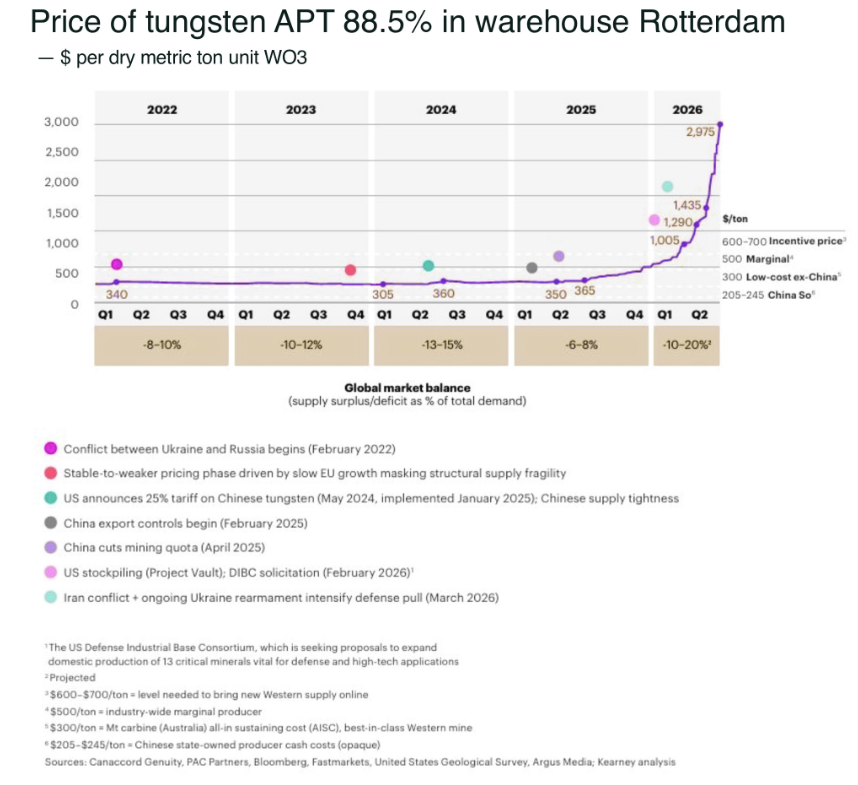
And China has tightened access to its own production after, in February 2025, Beijing introduced export licensing requirements for selected tungsten products. S&P Global's August 2026 report found that prices more than quadrupled between January-July in 2026.
(See our recent article Tungsten price shock signals deeper supply crisis)
US sourcing requirements are tightening too: from January 2027, defence procurement restrictions on covered tungsten products extend back to the mining and feedstock stages, generally excluding Chinese-origin material even when processed elsewhere, subject to specified exceptions.
Turning defence demand into secure mineral supply
The clearest evidence of the strategic urgency is Washington's growing intervention in mining finance — particularly domestic projects — including:
- MP Materials' July 2025 Pentagon partnership combined equity, a ten-year price floor for neodymium-praseodymium products, long-term magnet purchases and financing
- the Pentagon's commitment of up to US$450 million to Elmet for tungsten mining in Nevada, including an initial US$200 million investment closed in September 2026
- USA Rare Earth's June 2026 agreement with the Commerce Department provides access to approx US$1.6 billion, to support the Round Top mining and processing project in Texas and expand US metal and magnet production
- the Pentagon's US$750 million investment announced in August 2026 to secure rare-earth supply from Brazil's Serra Verde forms part of a US$1.55 billion financing structure supporting an offtake agreement, alongside a US$300 million Defense Logistics Agency purchase commitment and US$500 million bank commitment
- The Pentagon's approx US$174 million equity investment announced in August 2026 for Australian gallium production will support construction of a facility at Alcoa's Wagerup refinery, projected to produce 100 tonnes annually, through a partnership involving Australia and Japan
- The US International Development Finance Corporation's US$600 million investment in the US$1.8 billion Orion Critical Mineral Consortium closed in January 2026. By July, its board had approved a further US$900 million in financing to support a portfolio of critical-mineral projects, including a proposed investment in copper and cobalt operations in the DRC
Conclusion
Before America can reload its missile stockpiles, it must first reload its critical-mineral supply chains — potentially making the mining companies capable of delivering those materials at scale strategic pillars of the US defense industrial base.
* * *
Our Take
The Oregon Group's assessment that the US must "reload its critical-mineral supply chains" before accelerating the rearmament supercycle reinforces our focus on miners already producing these materials.
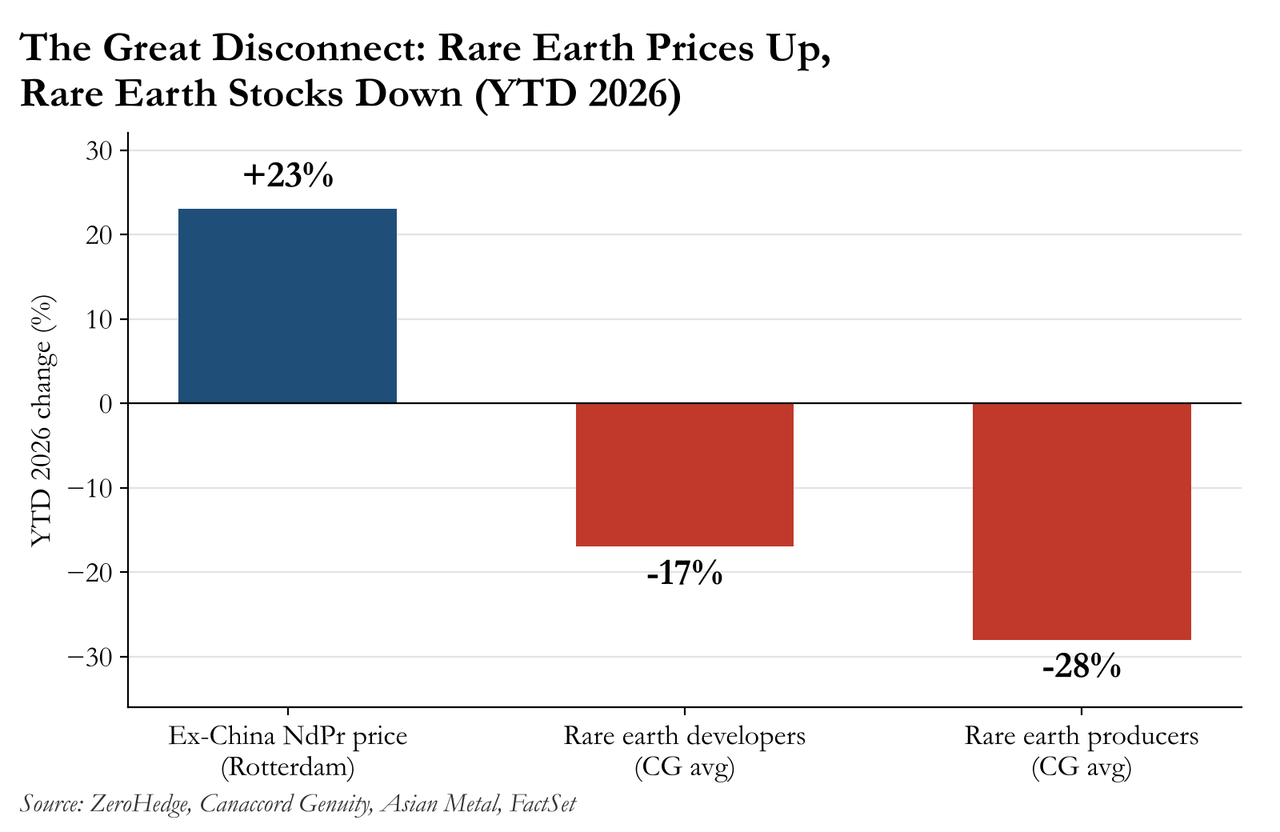
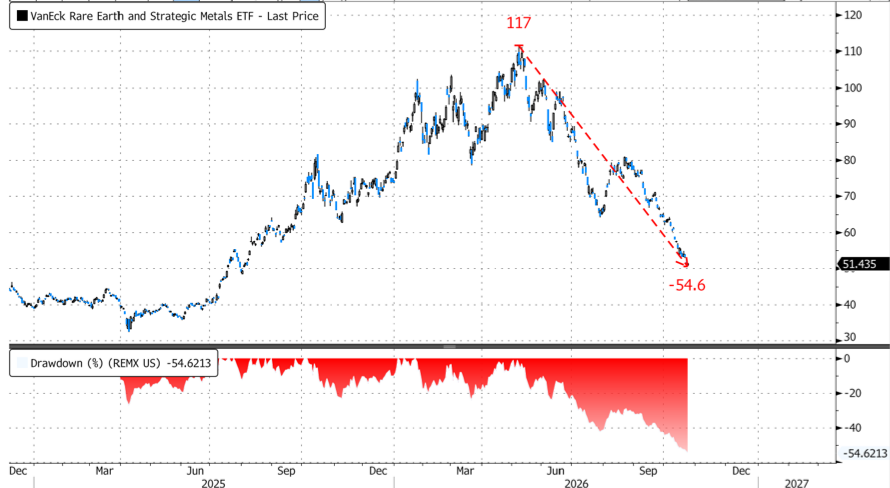
Yet a sharp disconnect has emerged between mining stocks and underlying spot metal prices.
We highlighted that divergence in "Great Rare Earth Disconnect," a view shared by William Blair analysts, which suggested that rare earth stocks trading at 52-week lows...
... may present a buying opportunity, arguing that optimism surrounding Chinese supply is "incorrect."